Manage your business
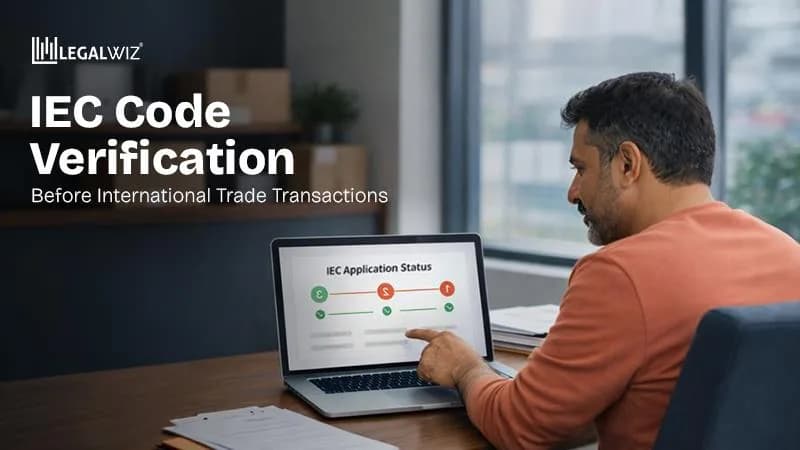
IEC Code Verification Before International Trade Transactions
International trade runs on documents, timelines, and trust. One missing detail can delay shipments or block payments.
2 min read
Returns prepared and filed by chartered accountants, from your invoices or straight out of your accounting software. Filing on time is also what lets your buyers claim their credit.
A few details, then secure checkout. Your expert takes it from there.
Starting at₹799+ Govt. Fees
 4.7/5 Ratings On Google
Prefer to talk to someone first?
What a return tells the government, which ones you owe, and what filing late actually costs.
Goods and Services Tax governs most of the indirect tax system in India, and every supplier registered under it has to report regularly. Which returns you file and how often depends on your turnover and on the scheme you are registered under.
A return tells the GST Network what came in and what went out: the supplies made and received, the tax collected and the tax paid. Alongside it you pay over the tax you collected from your customers, after deducting the input tax credit for the tax you already paid your own suppliers.
Filing late costs money twice. There is a late fee of ₹50 for each day of delay, ₹20 a day for a nil return, and interest at 18% a year on any tax outstanding. The second cost is not yours: a buyer cannot claim credit for the tax you charged them until you have filed, which is why larger buyers check a supplier’s compliance record before placing work.
The filing itself is quick. Reconciling the data, and finding what does not add up, is the work.
Data can be provided as a CSV, or extracted from any GST-ready accounting software such as Tally or QuickBooks. Where credentials are shared, the data can be fetched each period rather than sent.
The prescribed details from every invoice, including the HSN code for goods and the accounting code for services.
Everything supplied and everything received during the period being reported.
Expenses incurred in the period, which is where credit is most often left unclaimed.
What was collected from customers and what was already paid to suppliers. The difference is what you pay over.
Credit only flows once both parties have recorded the transaction. A buyer cannot claim the tax you charged them until you have filed, which is why a late supplier becomes a supplier a large buyer stops using.
A registered person cannot claim input credit on a return that has not been filed on time. The tax you already paid your own suppliers stays unclaimed until it is.
₹50 for each day of delay, ₹20 a day even where there is nothing to report, and interest at 18% a year on any tax outstanding. All of it is avoidable and none of it is recoverable.
The GST Network rates every registered person on how regularly they file and pay, and the rating is publicly visible. It is one of the things a prospective buyer looks at.
A regular taxpayer files the first two and the annual return. The rest are for specific categories, and most businesses will never touch them.
| Attribute | Who files it | How often |
|---|---|---|
| Every regular taxpayer | ||
| Every registered supplierReports the outward supplies made in the period, invoice by invoice. This is the return that puts credit into your buyer’s account. | Monthly or quarterlyMonthly for a business above the turnover limit. Quarterly for anyone in the QRMP scheme, with an optional monthly upload of invoices in between. | |
| Every registered supplierThe summary return. It reports the totals, sets off the input tax credit and is where the tax is actually paid. This is the filing most people mean by "my GST return". | Monthly or quarterlyFollows the same cycle as GSTR-1. Under QRMP the return is quarterly and the tax is paid monthly. | |
| Composition and special categories | ||
| Composition taxpayersA short statement of the turnover for the quarter and the tax payable on it, in place of the regular returns. | QuarterlyOne statement for each quarter of the financial year. | |
| Non-resident taxable personsA person from outside India making taxable supplies here. | MonthlyFor each month the registration is active. | |
| Input Service DistributorsAn office that receives invoices for input services and distributes the credit to its own branches. | MonthlyFor every calendar month or part of one. | |
| Deductors of TDS under GSTAnyone required to deduct tax at source under GST, which is mostly government departments and specified bodies. | MonthlyFor each month in which a deduction was made. | |
| E-commerce operatorsAn operator facilitating supplies through its platform, reporting the tax collected at source from its sellers. | MonthlyFor each month of operation. | |
| Once a year | ||
| Composition taxpayersThe annual return for a taxpayer in the composition scheme, filed on top of the quarterly CMP-08 statements. | AnnuallyOnce for each financial year. This used to be a quarterly return and is often still described as one. | |
| Regular taxpayersThe annual return, consolidating everything reported during the year. An Input Service Distributor, a casual or non-resident taxpayer, a composition taxpayer and a TDS or TCS deductor are outside it. | AnnuallyOnce for each financial year. | |
| Larger taxpayersA reconciliation statement between the annual return and the audited accounts, required above the prescribed turnover. | AnnuallyFiled with the annual return for the same year. | |
| Next step | ||
Swipe the table sideways. Open any attribute to read the detail behind both answers.

It has been more thank more a year since starter Please keep doing mindful practice. More power to LegalWiz Team !! Onwards and upwards. Special thanks to Ms Musarrat and Riddhi Thakor who kept on reminding the legal teams.
Satisfied with services
It is pleasure working with you legalwiz
They are a great help
I am totally satisfied with the services.
I am happy with the GST Return filings done by LegalWiz, I am very much thankful to Ms. Pooja Satyawadi and Mr. Pratik Shah for their help and guidance. Pooja has always reminded me to fill the form on time and Pratik has always guided me about any errors in the GST return form and how to fill it perfectly, without their help it would have been difficult for me to understand the GST form filing. Thanks to them.
Four things, and the last of them is the only one that changes each period.
The certificate issued to the registered person.
The log-in credentials of the registered person, used to file the return.
The DSC of an authorised partner or director. Required for an LLP and a company only.
The inward and outward taxable supplies for the period, with the invoice details. As a CSV, or extracted from your accounting software.
Step 01
Step 02
Step 03
Subject to government processing time.
Three working days from the day your data reaches us.
1 of 3 working days
2 of 3 working days
Subject to government processing time.
Leverage best deals offered by the industry leaders and experience mutual growth.
Still have a question? Our team is happy to help, at no charge and with no obligation to buy anything.
Every registered dealer files, whether or not they are a normal supplier, based on the transactions and activities in the business.
A registered person with nothing to report still files a nil return. Not filing is a default and attracts a fee whether or not there was any tax.
Yes, for a regular taxpayer. The annual return in GSTR-9 consolidates what was reported through the year and is filed on top of the periodic returns.
An Input Service Distributor, a casual or non-resident taxable person, a composition taxpayer and a TDS or TCS deductor do not file GSTR-9.
The prescribed details from your invoices, including the HSN code for supplies of goods and the accounting code for supplies of services.
The information also covers the sales, purchases and expenses for the period being reported.
Tax, and any penalty or fee, is accepted through:
Any supply: a sale, transfer, barter, exchange, licence, rental, lease or disposal of taxable goods or services, made or agreed to be made for a consideration.
You provide the transaction details each period, either manually in the format we share or as an extract from your accounting software.
Our experts review it, raise anything that does not reconcile, and file the return once it is confirmed.
As a CSV. If you use accounting software such as Tally or QuickBooks the details can be exported to CSV directly and used to prepare the return.
Any GST-ready software that can share or export data as CSV, Tally and QuickBooks and cloud-based accounting packages among them.
Yes. Where you share the credentials for the software you keep your books in, the data can be fetched each period and used to prepare the return.
The review. A qualified chartered accountant checks the information provided and identifies where the outward and inward supply data does not reconcile.
Where a discrepancy is found, the options for resolving it are set out before the return is filed rather than after.
International trade runs on documents, timelines, and trust. One missing detail can delay shipments or block payments.
2 min read
Every invoice, return, and system upload follows a fixed format, and quantity is one of the mandatory details when you file your GST return.
3 min read
After you register your company, the Ministry of Corporate Affairs issues a digital Certificate of Incorporation.
3 min read
Reviewed by a chartered accountant before anything is submitted.
Get started