E-Way Bill implemented w.e.f 01.02 for Transportation of Goods
The requirement of E-Way bill was deferred earlier by the GST Council, which is now made applicable since 1st Day of February, 2018 to India.
CS Prachi PrajapatiUpdated 2 min read
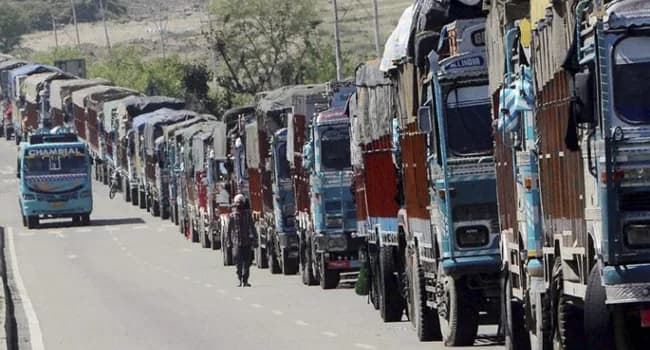
Table of contents7 sections
The requirement of E-Way bill was deferred earlier by the GST Council, which is now made applicable since 1st Day of February, 2018 to India. The concept of e-Way bill is specifically related to the movement of goods and hence applicable to transporters. E-Way Bill is an electronic way bill for movement of goods which can be generated on the e-Way Bill Portal.
Goods covered under e-Way Bill:
E-Way bill covers all type of movement of goods which also includes any rejection, return of sale, repairs and maintenance. Further, Job Work or material sent for Job Work with a challan of delivery. In case, the goods in movement through single one vehicle is not less than Rs 50,000/-, then generation of e-Way bill is mandatory for selected category of persons.
Person Responsible for generation of e-Way Bill:
A registered person will be required to issue an e-Way Bill on movement of goods of more than Rs 50,000/-. A registered person may also generate an e-Way bill at his own discretion, when value of goods less than Rs 50,000/-.
When a registered person is the receiver of goods but the supplier of goods is unregistered, then the receiver is required to generate the bill.
The transporter needs to generate e-Way bill for supply of goods by air, road or rail, if the supplier of goods has not generated an e-Way Bill.
Generation of e-Way Bill:
Generation of e-Way bill is final and it is not editable after its submission. Hence, Care shall be taken accordingly. E-Way bill is required to be generated through e-Way Bill Portal in two parts, where Part A requires details of receiver and details of Goods with its value. Part B will be the information of Transporter, where Name of Transporter, GR Number and Vehicle Number will be disclosed. Part B of e-Way Bill not is required when goods are dispatched for 10 km from place of supply through hand or rickshaw. Generation of consolidated e-Way bill will be allowed when transporter is carrying multiple consignments in a single vehicle. Further, following details will be required for generation of e-Way Bill:
ID of Transporter or Vehicle Number for Transport through road;
ID of Transporter, Transporter document number with date of documents for transport of goods by rail, air, or ship;
Invoice or Bill of Supply or Challan, of the consignment of goods, as the case may be.
Validity of e-Way Bill:
The e-Way bill generated will be valid till a specified time period as provided below:
Distance | Validity |
Up to 100 km | 1 day |
100 to 300 km | 3 days |
300 to 500 km | 5 days |
500 to 1000 km | 10 days |
More than 1000 km | 15 days |
Penalty:
Non-filing of e-Way bill will levy the penalty at the rate of 200% of GST in the invoice. The concept of e-Way Bill was not in force at pre-GST era. The Introduction of e-Way bill will lead to ease of transportation and movement of goods with unified system of transportation form one state to another state.
Written by
Company Secretary with a forte in content writing! Started as a trainee, she is now leading as a Content Writer and a Product Developer on technical hand of LegalWiz.in. The author finds her prospect to carve out a valuable position in Legal and Secretarial field.
All articles by CS Prachi PrajapatiServices related to this article
Everything here is handled online by our specialists, start to finish.
5 comments
Arvind kapoor
Part B of e-Way Bill not is required when goods are dispatched for 10 km from place of supply through hand or rickshaw.
If there is horse cart . Also we have no need to fill B part .
Monjima GhoshLegalWiz.in team
Hi Arvind, that's a great question. Modes of transport, such as horse carts, come under 'non-motorized conveyance'. No e-Way bills are required for non-motorized modes of conveyance. For more details on this you can read section 138 (14) of the CGST rules; you can find the same on this link: https://cbic-gst.gov.in/pdf/amended-01012022-CGST-Rules-2017-Part-A.pdf
Himanshu Garg
Part B of e-Way Bill not is required when goods are dispatched for 10 km from place of supply through hand or rickshaw.
How can e-way bill will generate without transporter id or vehicle number?
Anonymous
Nice blog and all details are mentioned related to gst eway bill India
Rajeev Sharma
Thanks for sharing this informative information regarding. I would like to know if the automatic generation of e way bill was implemented.